

By Majeed Salaam
Nigeria’s financial inclusion agenda must move beyond expanding access to bank accounts and digital financial services to ensuring that participation translates into economic opportunities, stronger household resilience and business growth, stakeholders have said.
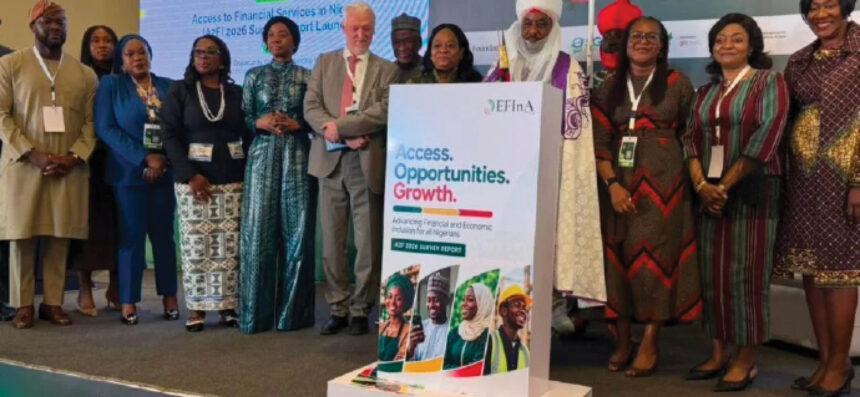
The Board Chair of Enhancing Financial Innovation and Access (EFInA), Dr. Agnes Martins, made the call in Abuja recently at the launch of the 2026 Access to Financial Services in Nigeria (A2F) survey report.
Held under the theme, ‘Access, Opportunity, Growth: Advancing Financial and Economic Inclusion for All Nigerians’, the event examined the next phase of financial inclusion against changes in Nigeria’s economy, technology and financial services landscape.
Dr. Martins said the A2F survey had provided nationally representative evidence on Nigerians’ experiences with financial services since 2008, making it an important tool for understanding changing patterns of financial participation.
She said EFInA’s 2024 to 2029 strategy was designed to ensure that Nigerians were not only financially included but also economically empowered, with greater emphasis on usage, quality and impact.
“Access is only the beginning of the journey. It is not the destination,” she said.
According to her, the key question for policymakers and financial service providers should be whether participation in the financial system is expanding opportunities for Nigerians and helping households and businesses manage their finances more effectively.
The 2026 survey, she said, was particularly relevant because Nigerians’ financial needs had evolved alongside changes in income patterns, digital channels and the wider economy since the previous survey in 2023.
Dr. Martins cautioned against designing financial policies and products around an “average” consumer, noting that financial needs differ according to income, gender, location, age and economic activity.
“The evidence must help us understand not only where the gaps are, but what is driving them,” she said.
She urged policymakers, regulators, financial institutions, governments and development partners to apply the survey findings in developing policies, products and investments that address specific barriers to financial participation.
The emphasis on impact was also reflected in the pension sector, where significant gaps remain despite recent growth in participation.
The Director-General of the National Pension Commission (PenCom), Ms. Omolola Oloworaran, said pension inclusion should be assessed by its contribution to financial security and wellbeing rather than simply by the number of accounts opened.
“Opening a pension account is not by itself pension inclusion,” she said.
Ms. Oloworaran disclosed that pension participation had increased from 7.8 percent of Nigerian adults in 2023 to 9.1 percent in 2026. Despite the improvement, she noted that about nine in every 10 adults remained outside formal pension arrangements.
The excluded population cuts across large sections of the informal economy, including traders, farmers, mechanics, drivers, tailors, hairdressers and digital workers.
For PenCom, expanding coverage will therefore require pension products that reflect how Nigerians actually earn and manage income.
Ms. Oloworaran said the commission was committed to expanding coverage through the Personal Pension Plan (PPP), but called for a dedicated pension inclusion model that would identify what encourages people to begin and sustain pension savings.
She also proposed a pension inclusion map showing exclusion patterns by geography, gender, age, occupation and income.
Such evidence, she said, would help policymakers understand why pension gaps persist and design more targeted interventions.
The PenCom chief further advocated experimentation with digital onboarding, accredited pension agents and transaction-based savings. She said matching incentives and behavioural approaches should also be tested and independently evaluated to determine their effectiveness.
An important concern, she noted, is that participation without sustained contributions may create a misleading picture of inclusion.
“An unfunded pension account cannot provide adequate retirement security,” Ms. Oloworaran said, stressing that the more meaningful measure was consistent savings and sufficient accumulation for retirement.
Her position mirrors the broader message from the A2F launch: expanding access is only one stage of financial inclusion. The more consequential question is what Nigerians can do with the financial tools available to them.
For the financial inclusion ecosystem, the 2026 A2F findings therefore provide a basis for examining not only who has access to financial services, but who is using them, what benefits they derive and where exclusion continues to limit economic participation.
The challenge ahead is to convert wider financial participation into measurable improvements in livelihoods, enterprise growth and long-term financial security.