

Nigeria’s fiscal and monetary policies increasingly operate on the same pressure points: inflation, borrowing costs, liquidity, exchange rates, government financing and economic growth. The recent Memorandum of Understanding (MoU) between the Central Bank of Nigeria (CBN) and the Federal Ministry of Finance seeks to bring these two policy arms into a more structured working relationship. Its significance lies not in creating a new partnership, but in formalising how two institutions with separate mandates exchange information, plan and respond to economic shocks. As Nigeria moves towards inflation targeting, the effectiveness of this framework will depend on how consistently it translates coordination into coherent economic decisions. Enam Obiosio writes…
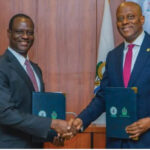
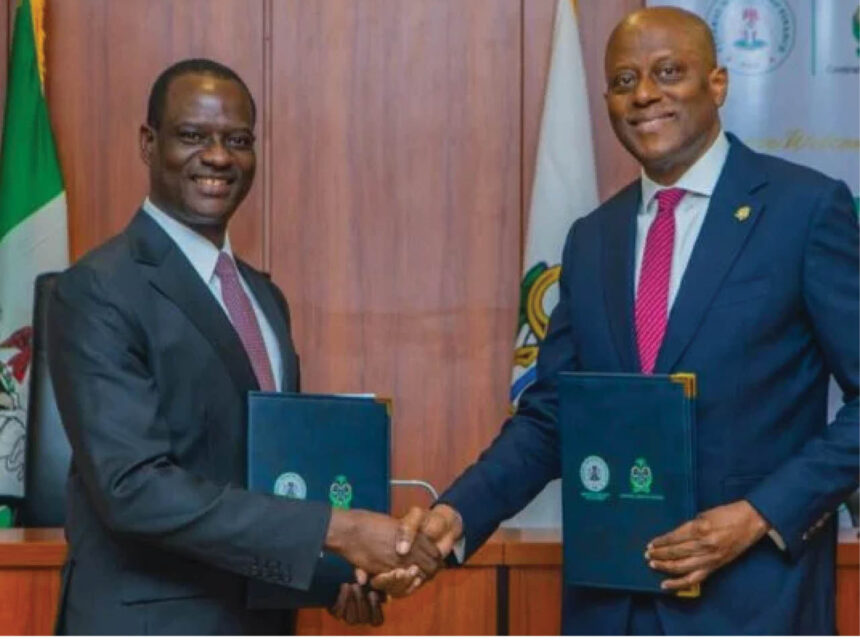
The Central Bank of Nigeria (CBN) and the Federal Ministry of Finance recently signed the MoU in Abuja, formalising a framework for closer fiscal and monetary policy coordination.
Mr. Olayemi Cardoso, Governor of CBN, described the agreement as a significant step towards stronger macroeconomic management, lasting economic stability and sustainable prosperity.
He stressed that the MoU was more than a document. It represents a commitment to deeper collaboration between institutions whose decisions frequently affect the same economic outcomes.
“Fiscal and monetary policies remain two important and confidential instruments for the management of a modern economy,” Mr. Cardoso said.
Fiscal policy operates through government expenditure, taxation and borrowing, while monetary policy influences liquidity, interest rates and monetary conditions. Although their instruments and mandates differ, their effects often overlap.
Government borrowing, for instance, can influence liquidity and interest rates. Monetary tightening can increase government financing costs. Public spending can affect demand, while exchange rates and tariffs can influence prices and government revenue.
“When these policies work together in harmony, their combined impact is far greater than their individual efforts,” he said.
The new framework does not create a relationship that previously did not exist. The CBN and the Ministry of Finance have collaborated for decades on inflation, debt sustainability, budget financing, exchange rate stability and responses to economic shocks.
What changes is the structure around that relationship.
“This memorandum provides for a structured framework for regular consultation, information exchange, and policy coordination,” Mr. Cardoso said.
The arrangement will cover government cash management, debt issuance planning, liquidity forecasting, macroeconomic analysis and periodic policy consultations.
These areas matter because fiscal decisions can alter the monetary environment in which businesses, households and investors operate. Better coordination could allow both institutions to anticipate the effects of major financing and spending decisions rather than responding after pressures have already emerged.
The agreement also comes as the CBN advances its transition towards an inflation-targeting framework.
Mr. Cardoso argued that inflation targeting requires more than an effective central bank. It also depends on a fiscal environment that does not undermine monetary objectives.
“Across the world, the success of inflation targeting is known to rest not only on the effectiveness of monetary policy, but also on the existence of a supportive fiscal environment,” he said.
This places fiscal discipline and monetary credibility within the same policy conversation. If government spending, borrowing or cash injections generate additional demand or liquidity pressures, monetary policy may face a heavier burden in containing inflation. Conversely, more predictable fiscal operations can support clearer monetary transmission.
On his on part, Mr. Taiwo Oyedele, Minister of Finance and Coordinating Minister of the Economy, emphasised that coordination should not be confused with a loss of institutional independence.
“Good economic management requires independent institutions, but independence does not mean isolation,” he said.
“Fiscal and monetary authorities have distinct mandates, but we serve the same economy.”
Mr. Oyedele’s argument points to the central principle behind the MoU. Independence determines who makes particular policy decisions. Coordination determines how those decisions are informed and how their consequences are managed across the economy.
He identified several areas where the two policy spheres naturally intersect.
“Government borrowing affects liquidity and interest rates. Monetary policy affects the government’s financing costs. Tariffs and exchange rates affect prices and revenue. Spending affects demand. Agricultural quality affects food inflation,” he said.
“So, our mandates are distinct, but our outcomes are interconnected.”
That interconnection becomes more important when Nigeria faces external shocks.
Mr. Muhammad Abdullahi, CBN Deputy Governor, Corporate Services, cited developments in the Middle East as an example of how a single international event can generate simultaneous fiscal and monetary consequences.
Disruptions to energy and shipping routes can affect oil prices, insurance costs, global inflation expectations and international financing conditions.
For Nigeria, higher oil prices can strengthen export earnings, government revenue and foreign exchange inflows. But higher energy and insurance costs can also increase domestic production and transportation expenses. If global inflation rises, international interest rates and financing conditions may tighten.
“One external shock can arrive simultaneously at the doors of fiscal and monetary policy,” Mr. Abdullahi said.
The implication is straightforward. Fiscal authorities need to assess the effect of an external shock on revenue, expenditure, financing and debt. Monetary authorities must simultaneously consider inflation, liquidity, reserves, exchange rates and broader financial conditions.
A coordinated response can help prevent these assessments from occurring in isolation.
The new agreement seeks to strengthen these relationships through clearer processes and defined areas of engagement.
For businesses, the potential importance is largely indirect but significant. Fiscal and monetary decisions influence the cost of capital, consumer demand, foreign exchange conditions, government contracts and investment decisions. Greater policy coherence could therefore reduce some of the uncertainty created when major economic decisions move in different directions.
For investors, the issue is similarly tied to predictability. Fiscal sustainability, monetary credibility and foreign exchange management are interconnected components of the macroeconomic environment used to assess investment risk.
For government, improved coordination could strengthen debt planning and cash management while helping policymakers understand the monetary implications of fiscal decisions.
But the signing itself does not guarantee these outcomes.
The effectiveness of the framework will depend on implementation. Regular consultations must produce useful information. Shared data must improve forecasts. Debt issuance and government cash management must be coordinated with liquidity conditions. Policy discussions must take place early enough to influence decisions.
The distinction between coordination and control will also remain important. The CBN must retain its statutory monetary responsibilities, just as fiscal authorities retain responsibility for taxation, expenditure and public borrowing.
The value of the agreement, therefore, will be seen in how effectively the two institutions manage this balance.
Nigeria’s recent economic experience has demonstrated that fiscal and monetary pressures rarely remain within institutional boundaries. Inflation affects household purchasing power and business costs. Interest rates affect both private investment and government debt servicing. Exchange rate movements influence import costs, revenue and monetary conditions. Oil prices affect public finances while simultaneously influencing foreign exchange supply.
These connections make fragmented policy responses increasingly difficult to sustain.
That is the central significance of the agreement.
It does not introduce fiscal or monetary policy to Nigeria. It formalises the channel through which the two sides are expected to understand, anticipate and manage their interaction.